One of the biggest issues companies face is retaining their best employees. Benefits such as maternity leave, lengthy vacation, group retirement plans and healthcare have come to be expected, but they are costly and do not always keep great employees for the long-term. Is there a better option?
Rewarding Your Achievers
When you increase the types of benefits mentioned above, owners must offer the increase to every single team member. Effectively you are paying the same cost to all your workers, even the ones you don’t want to replicate.
That is why for key employees, owners should consider non-qualified deferred compensation (NQDC) plans, also known as “golden handcuffs.” Through NQDC, owners can provide more customized benefits to select individuals.
When offering these plans, they do not always have to be expensive. In fact, given the short- and long-term retention that is likely to come about, these benefits can be quite economical!
When developing this plan, you will want to include a rolling vesting period. A rolling vesting period creates a single vesting schedule each year for the new contribution.
Here’s an example:
Marilyn, one of your high-achieving team members, receives a bonus of 20 percent each year with a three-year rolling vesting period starting in 2019.
The following year, Marilyn would receive another bonus of 20 percent with a three-year rolling vesting period, and so forth.
Marilyn does not receive her first bonus until 2022. The next bonus would not be delivered until 2023, and so forth.
By delivering these benefits to Marilyn in the future, it may keep her committed to the company longer.
Designing Your Plan
Any NQDC plan needs to have forfeiture conditions. If there is no risk of losing the benefits, then there is no opportunity cost. When people know what they will be giving up in the future by leaving, it makes them hesitate and most of the time they realize the cost outweighs the potential benefits of another opportunity.
In the example above Marilyn would lose out on the unvested bonuses if she left within a certain time period. Other common forfeitures include non-compete, non-solicitation, and non-disclosure clauses.
These clauses prevent participants not only from going to the competition within a specified radius, from taking key employees or customers with them, and disclosing any key information about the company.
Cost vs. Benefit
You must incorporate key performance metrics when implementing an NQDC plan. This allows you to evaluate the plan’s impact and effectiveness. The company does not have to provide the benefit unless the requirements are met which allows for the plan to pay for itself.
For example, let’s say a company’s sales are at $1,000,000 and your goal is to be at $1,200,000. If you are willing to give a 10 percent bonus to an employee for sales over $1,200,000, the growth in sales has paid for the benefit to the key employee.
Summary of Smarter Ways to Reward Your Best Employees
These are the foundations for a strong, healthy NQDC plan for any organization: have a vesting period, incorporate forfeitures, and utilize metrics.
You can create a loyalty plan that helps your company grow, delivers value to your employees, and protects your company from losing its greatest asset: the employees.
Consider working with an expert in developing a plan tailored to your needs and goals.
About the Financial Author
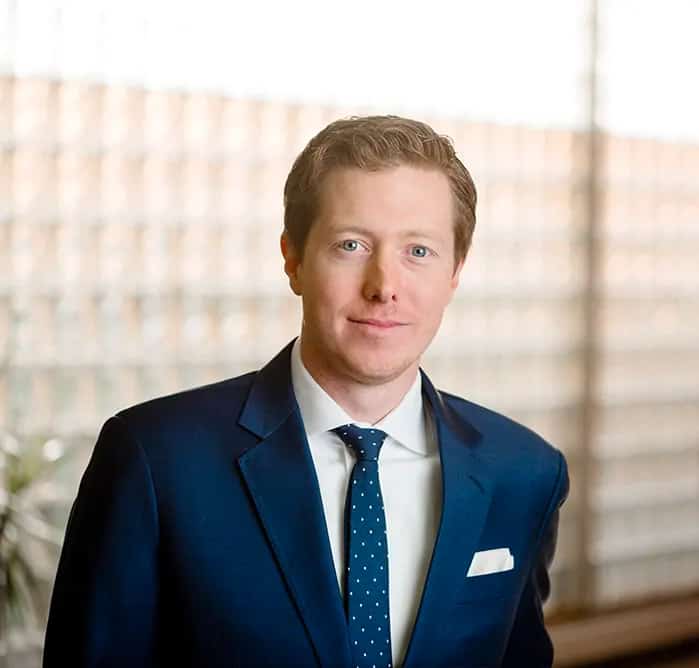
Alexander Langan, J.D., is the Chief Investment Officer at Langan Financial Group. In this role, he manages investment portfolios, acts as a fiduciary for group retirement plans and consults with clients regarding their financial goals, risk tolerance and asset allocation.
With a focus on ERISA Law, Alex graduated cum laude from Widener Commonwealth Law School. He then clerked for the Supreme Court of Pennsylvania and worked in the Legal Office of the Pennsylvania Office of the Budget, where he assisted in directing and advising policy determinations on state and federal tax, administrative law, and contractual issues.
Alex is also passionate about giving back to the community and has helped establish The Foundation of Enhancing Communities’ Emerging Philanthropist Program, volunteers at his church, and serves as a board member of Samara: The Center of Individual & Family Growth. Outside of work and volunteering, Alex enjoys his time with his wife Sarah and their three children, Rory, Patrick, and Ava.
About Langan Financial Group
For everything you’ve built.
Your savings. Your business. Your family’s future. Each deserves thoughtful planning that starts with what matters to you.
Langan Financial Group provides financial planning and investment management for individuals, families, and business owners. With offices in Camp Hill and York, Pennsylvania, we serve clients throughout Central Pennsylvania.
We help you work through questions about retirement income, investment decisions, Social Security, and how taxes may affect your financial plan. Our approach starts with understanding your goals, your financial picture, and your comfort with investment risk. From there, we help you evaluate your options and develop a plan that can evolve as your life changes.
We also help businesses and organizations evaluate workplace retirement plans and understand their responsibilities as plan sponsors.
Disclosures
The information in this material is not intended as tax or legal advice. Please consult legal or tax professionals for specific information regarding your individual situation. The opinions expressed and material provided are for general information.