The latest Social Security report warns that the trust funds could run out by 2034—one year sooner than expected. If nothing changes, everyone on Social Security could see their monthly checks cut by about 20%. This news has many people worried about their retirement.
What’s Happening With Social Security?
Social Security is funded by payroll taxes from workers and employers. Right now, more money is going out to retirees than is coming in from workers.
By 2034, the trust funds that help cover the gap is predicted to be emptied. If Congress doesn’t act, benefits will be cut by about 20% for everyone.
Example:
If you get the average Social Security check of $1,976 per month, you could see it drop to about $1,600 per month.
Common Questions About Social Security Answered
Will Social Security go away?
No, but the checks may be smaller. Even if the trust funds run out, payroll taxes will still cover about 80% of promised benefits.
Do I need to change my retirement plans?
Yes, it’s smart to plan for smaller Social Security checks. The sooner you adjust, the better off you’ll be.
What Should You Do If Social Security Is Reduced? Advice for Every Generation
Baby Boomers (Ages 60+)
- Already retired?
- Review your budget and plan for a 20% cut in Social Security income.
- Consider cutting back on spending or using other savings to fill the gap.
- If possible, work part-time or use Roth IRA withdrawals for extra cash.
- Still working?
- Wait as long as you can to claim Social Security. Every year you wait (up to age 70) increases your benefit by 8%.
- Max out your 401(k) and IRA contributions, especially “catch-up” contributions.
Generation X (Ages 44–59)
- Boost your savings.
- Aim to save 20–25% of your income for retirement.
- Use retirement calculators to see what your plan looks like with 20% less Social Security.
- Think about working a few extra years. Even two more years can make a big difference.
- Use tax-advantaged accounts.
- Health Savings Accounts (HSAs) and Roth IRAs can help your money grow faster and be more tax-efficient.
Millennials (Ages 28–43)
- Invest for growth.
- Each person’s scenario is different. If possible, you can put most of your retirement savings in stocks and index funds. The longer your money grows, the better.
- Don’t count on Social Security as your main income. Treat it as a bonus.
- Build other income streams.
- Consider side gigs, rental properties, or dividend-paying stocks to supplement your retirement income.
Generation Z (Ages 12–27)
- Start saving early.
- Save at least 15% of your income as soon as you start working.
- Even small amounts add up over time thanks to compound interest.
- Focus on your career.
- Invest in education and skills to boost your earning power. Higher pay means you can save more for retirement.
What Could Change?
Congress could fix Social Security by raising taxes, changing benefits, or both. But waiting for lawmakers to act is risky. It’s best to take control of your own retirement plan now.
Next Steps
- Meet with a financial advisor to review your plan and adjust for possible Social Security cuts.
- Update your retirement budget to see how a 20% cut would affect you.
- Stay informed about Social Security news and changes.
Final Thoughts
The news about Social Security is a wake-up call, not the end of the world. By saving more, investing wisely, and planning ahead, you can build a secure retirement—no matter what happens in Washington.
About the Financial Planning Author
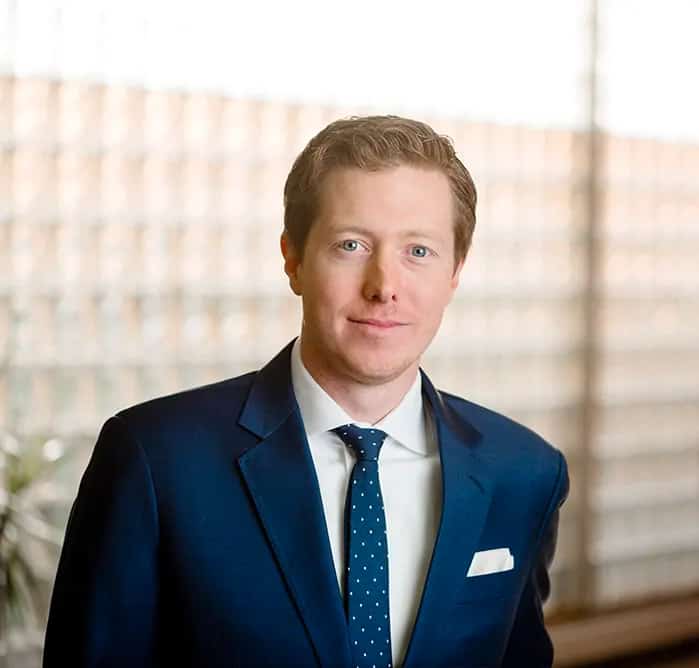
Alexander Langan, J.D., serves as the Chief Investment Officer at Langan Financial Group. In this role, he manages investment portfolios, acts as a fiduciary for group retirement plans, and consults with clients regarding their financial goals, risk tolerance, and asset allocation.
With a focus on ERISA Law, Alex graduated cum laude from Widener Commonwealth Law School. He then clerked for the Supreme Court of Pennsylvania and worked in the Legal Office of the Pennsylvania Office of the Budget, where he assisted in directing and advising policy determinations on state and federal tax, administrative law, and contractual issues.
Alex is also passionate about giving back to the community, and has participated in The Foundation of Enhancing Communities’ Emerging Philanthropist Program, volunteers at his church, and serves as a board member of Samara: The Center of Individual & Family Growth. Outside of work and volunteering, Alex enjoys his time with his wife Sarah, and their three children, Rory, Patrick, and Ava.
About Langan Financial Group: Financial Advisors
For everything you’ve built.
Your savings. Your business. Your family’s future. Each deserves thoughtful planning that starts with what matters to you.
Langan Financial Group provides financial planning and investment management for individuals, families, and business owners. With offices in Camp Hill and York, Pennsylvania, we serve clients throughout Central Pennsylvania.
We help you work through questions about retirement income, investment decisions, Social Security, and how taxes may affect your financial plan. Our approach starts with understanding your goals, your financial picture, and your comfort with investment risk. From there, we help you evaluate your options and develop a plan that can evolve as your life changes.
We also help businesses and organizations evaluate workplace retirement plans and understand their responsibilities as plan sponsors.
Disclosure
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice.
Please consult legal or tax professionals for specific information regarding your individual situation.
The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security.
No Fields Found.