What is a Solo 401(k)? Understanding This Self-Employed Retirement Plan
A 401(k) Plan is a type of retirement savings plan where participants contribute money from their earned wages into a retirement investment account. In a traditional 401(k), the contribution is taken from the paycheck before taxes are taken out.
The account can be invested in the market and will grow tax-free until retirement. The company may or may not provide a match to the participant.
The Solo 401(k), also called a one-participant 401(k) is a retirement plan designed for a business with no employees. The plan allows the owner to save a larger portion of their salary compared to participation in a traditional 401(k) or a SIMPLE IRA. The plan can also include the spouse of the owner.
Eligibility Requirements for a Solo 401(k): Who Can Open One?
A Solo 401(k), is only available if the business has no employees. The one caveat to this is that if the owner employs their spouse, the spouse may also participate in the Solo 401(k) plan
If the business has any non-owner employees, the business is not eligible for a solo 401(k).
Solo 401(k) Contribution Limits: Maximize Your Retirement Savings
In a solo 401(k), contributions are limited to $69,000 for 2024, with the ability of an additional catch-up contribution of $7,500 if over the age of 50. This brings the total limit for a Solo 401(k) plan to $76,500 if over the age of 50.
As of November 1st, 2024, the IRS has not released information on potential changes for solo 401(k) contributions in 2025.
Since you are both the owner and the employee of the company, you are able to contribute as the employee and the employer. Employee contributions are capped to the lesser of $23,000 or 100% of your wages in 2024. The previously mentioned catch-up provision applies to the employee contributions, so if over the age of 50, this increases to $30,500.
Employer contributions are referred to as employer nonelective contributions and are limited to 25% of compensation.
Advantages of a Solo 401(k) for Small Business Owners: Why Choose This Plan?
The largest benefit of a Solo 401(k) is allowing small business owners to contribute portions of their salary to a retirement account. In addition to maximizing retirement savings, a Solo 401(k) also:
- Larger contribution limits with a maximum of $69,000 (or $76,500 if over 50) in 2024
- When an employee contributes pre-tax into a solo 401(k), the contributions will offset your taxable income, lowering it by the amount contributed to the plan
- Even though it states no employees are allowed, a spouse is allowed to participate in the plan
- Discrimination testing is non-applicable therefore not required
- Annual From 5500 filing is not always necessary, it is dependent on the plan balance
- As long as the total value of the plan is under $250,000, filing a Form 5500 is not required
- Loans can be permitted, allowing the owners to borrow from the plan
These advantages create a 401(k) plan that is easier to administer than a standard 401(k) plan.
Downsides of a Solo 401(k) for Single Entrepreneurs
- If a business has plans to grow and hire new employees, a Solo 401(k) is not suitable, because adding an employee would make the retirement plan ineligible.
- Withdrawals from a solo 401(k) will be penalized if the participant has not reached retirement age yet.
- If the business is set up as a sole proprietorship or a partnership, profit-sharing calculations can be difficult. This can be solved by working with a Third-Party Administrator to ensure the plan is being utilized to the fullest.
How to Set Up a Solo 401(k) for Solo Entrepreneurs
To establish a solo 401(k), you will need to acquire an Employer Identification Number (EIN), an adoption agreement, and an application for the account. These can be completed by working with a financial advisor and a third-party administrator. Once these are created and approved, you will be able to begin contributing.
When working with a financial advisor for a solo 401(k), they should also provide an Investment Policy Statement (IPS) to guide the investments of the plan. An IPS ensures that the account owner’s investment goals, risk tolerance, and asset allocation strategy are clearly defined and follow a structured and disciplined approach to managing retirement savings.
Key Takeaways: Making the Most of Your Solo 401(k) Plan for Small Business Owners
Offering a retirement plan is a great way to retain talent and incentivize employees to plan for retirement. For small businesses, it is important to analyze what the goals of the business are to choose the appropriate retirement plan.
If the only employees are the owner and a spouse, a Solo 401(k) may be the best option by having high contribution limits and relatively simple requirements to establish the plan.
If the company has employees, but less than 101, they can offer a SIMPLE IRA to encourage employees to save while keeping administrative costs low.
A 401(k) plan is also an option if the employer is looking to contribute more to employee accounts than the SIMPLE IRA. The costs and maintenance associated with the plan are higher than the Solo 401(k) or SIMPLE IRA, but for a company positioned to grow and wants to retain talent, it is a great option.
About the Financial Authors
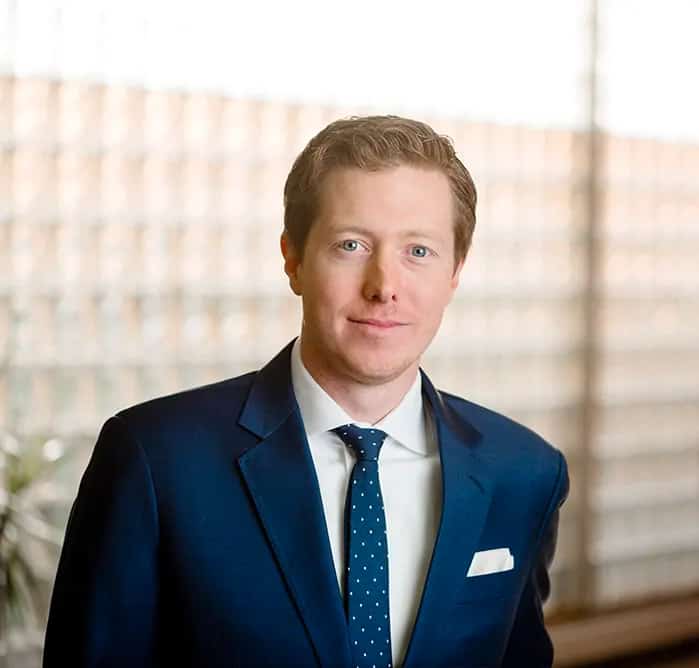
Alexander Langan, J.D., serves as the Chief Investment Officer at Langan Financial Group. In this role, he manages investment portfolios, acts as a fiduciary for group retirement plans, and consults with clients regarding their financial goals, risk tolerance, and asset allocation.
With a focus on ERISA Law, Alex graduated cum laude from Widener Commonwealth Law School. He then clerked for the Supreme Court of Pennsylvania and worked in the Legal Office of the Pennsylvania Office of the Budget, where he assisted in directing and advising policy determinations on state and federal tax, administrative law, and contractual issues.
Alex is also passionate about giving back to the community, and has participated in The Foundation of Enhancing Communities’ Emerging Philanthropist Program, volunteers at his church, and serves as a board member of Samara: The Center of Individual & Family Growth. Outside of work and volunteering, Alex enjoys his time with his wife Sarah, and their three children, Rory, Patrick, and Ava.
Harry Claypool currently serves as an Associate 401(k) Advisor at Langan Financial Group where he assists Alex in servicing retirement plans, preparing plan reviews, and handling administrative work.
In his free time, Harry enjoys visiting new restaurants, spending time with friends and family, and watching the Eagles.
About Langan Financial Group: 401(K) Financial Advisors
For everything you’ve built.
Your savings. Your business. Your family’s future. Each deserves thoughtful planning that starts with what matters to you.
Langan Financial Group provides financial planning and investment management for individuals, families, and business owners. With offices in Camp Hill and York, Pennsylvania, we serve clients throughout Central Pennsylvania.
We help you work through questions about retirement income, investment decisions, Social Security, and how taxes may affect your financial plan. Our approach starts with understanding your goals, your financial picture, and your comfort with investment risk. From there, we help you evaluate your options and develop a plan that can evolve as your life changes.
We also help businesses and organizations evaluate workplace retirement plans and understand their responsibilities as plan sponsors.
Disclosure
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice.
Please consult legal or tax professionals for specific information regarding your individual situation.
The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security.