The Setting Every Community Up for Retirement Enhancement Act 2.0, or SECURE 2.0 became legislation on December 29th 2022 through the larger “Consolidated Appropriations Act of 2023“, the official name for the budget bill of 2023.
This long overdue update to the retirement industry has implemented many (over ninety!) changes that will help every day Americans better prepare for retirement. Although there are many different provisions, some of them will not take effect until the late 2030s.
Key Changes Introduced by SECURE Act 2.0: What You Need to Know
The passage of SECURE 2.0 expands upon the original retirement provisions of the SECURE Act, which was passed in late 2019.
Most notably, the original SECURE Act included a provision that increased the age required for minimum withdraws to begin.
The new SECURE Act builds upon the original act to ensure retirement legislation evolves with retirement demands.
Boosting Small Business Retirement Plans: New Tax Credits Under SECURE Act 2.0
The original SECURE Act granted startup businesses with up to 100 employees a tax credit equal to 50% of administrative costs, capped annually at $5,000.
The SECURE Act 2.0 broadened the tax credit for businesses with 50 or fewer employees. Thos companies that starts a 401(k) after December 31st, 2022, can receive a credit for 100% of the administrative costs of establishing a retirement plan, up to $5,000.
A company that has 51 or more employees is only eligible for the original SECURE Act provision of 50% capped at $5,000.
Addressing Student Loan Debt: How SECURE Act 2.0 Supports Young Workers
Younger employees are facing a common problem of having to choose between saving for retirement or paying their student loans.
Under this provision, beginning in 2024, employers will have the option of matching employee payments to student debt with contributions to their retirement plan.
Expanding Access: New Eligibility Requirements for Retirement Plans Under SECURE Act 2.0
Secure Act continues to change retirement plans. It is expanding access to part time employees through eligibility requirements. Part-time employees will need two consecutive years of service with 500 hours in each year, cutting off the previous three-year requirement.
Another new introduction is that employers are now able to encourage participation in the retirement plan with small financial incentives such as low-dollar gift cards.
This is detailed in section 113, and states that “de minimus” financial incentives can be made, but not from plan assets. The bill does not further define what constitutes “low-dollar”.
Automatic Enrollment Made Easy: SECURE Act 2.0’s Impact on New Retirement Plans
Since 2025, employers with a new 401(k) or 403(b) plan (established after December 29, 2022) are required to automatically enroll eligible employees. The initial deferral must be between 3% and 10%, increasing by 1% each year until it reaches at least 10% (but no more than 15%). Employers with 10 or fewer employees, businesses less than three years old, church plans, and government plans are exempt.
Roth Accounts Reimagined: Key Updates from SECURE Act 2.0
Starting in 2024, Required Minimum Distributions (RMDs) are no longer required for any type of Roth account. This will include Roth 401(k)s, Roth 403(b)s, governmental Roth 457(b)s, and Roth contributions to a Federal Thrift Savings Plan currently requiring a retiree to take RMDs beginning at age 72.
The reasoning behind this change is to create uniformity between retirement plan Roth accounts and personal Roth IRAs. It is also important to note that this provision is not just eliminating RMDs for upcoming retirees, it is also removing it for retirees currently taking a RMD.
Currently, a Roth 401(k) account inside of a 401(k) or other type of group retirement plan, is required to begin RMDs when the owner turns 72. This created a clear advantage for Roth IRAs, as they did not require RMDs until the owner’s death.
With the new change, it levels the field between the Roth IRA and the Roth 401(k), requiring a more in-depth decision-making process of what to do with a Roth account from a group retirement plan.
SIMPLE IRAs have only allowed for traditional contributions to a SIMPLE IRA. With section 601 of the SECURE 2.0 act, employees are now able to contribute into a Roth account inside of a SIMPLE IRA or SEP retirement plan.
In addition to the changes for employee contributions, section 604 of the SECURE Act 2.0 allows for employer contributions to a Roth 401(k) or 403(b). Since these will be going into a Roth account, having taxes taken out of, they cannot be bound by a vesting schedule.
Accessing Your Funds: Emergency Withdrawal Options Under SECURE Act 2.0
Some important changes to retirement plans are the way that retirement assets can be used prior to retirement age:
Beginning on January 2nd, 2024:
- One time a year, participants are able to withdraw $1,000 for emergency personal or family expenses and be exempt from the 10% early withdraw penalty.
- Employees can establish a Roth emergency savings account, allowing up to $2,500 per participant.
- This can be deferred from their paycheck, just like a normal retirement plan contribution.
- They are then allowed four penalty-free withdrawals a year.
- Survivors of domestic abuse can withdraw the lesser of $10,000 or 50% of their retirement account without incurring a 10% penalty. They will be able to repay the borrowed amount over 3 years.
Effective immediately
- If an employee lives in an area that is in a federally declared state of disaster, they are allowed to withdraw up to $22,000 from their retirement account without penalty.
Maximizing Contributions: New Catch-Up Limits for Retirement Savings
Since 2025, 401(k), 403(b), and governmental 457 plan participants between ages of 60 to 63 can make a larger catch-up contribution: $11,250 in 2026, compared with $8,000 for participants age 50 and older.
For SIMPLE IRA and SIMPLE 401(k) plans at employers with 25 or fewer employees, those age 50 or older can contribute 10% more for their catch-up contribution.
For employers with 26 to 100 employees, if the employer provides a 4% matching contribution OR a 3% employer contribution, the employee can defer a higher limit.
Beginning in 2026, employees whose prior-year FICA wages exceeded $150,000 must make any catch-up contributions as Roth contributions.
RMD Revisions: What the SECURE Act 2.0 Means for Your Withdrawals
The original SECURE Act changed the age which a retiree must begin taking distributions from their retirement plan from 70 ½ to 72. The newly passed SECURE Act 2.0 is effective for the 2023 tax year and raises this age even further;
- For people who turn 72 after December 31st, 2022 OR 73 before January 1st, 2033, their RMDs must begin at 73
- For people who turn 74 after December 31st, 2032, RMDs must begin at age 75
Therefore; if a retiree is turning 72 during 2023 or later, they will begin their RMDs at 73. If a retiree is turning 74 during 2033, RMDs will begin at the age of 75.
In addition to increasing age RMDs initiate, the bill also reduces the tax for not taking the full RMD from 50% to 25% with the opportunity to reduce the penalty even further. If the missed RMD is corrected within the allowed amount of time, it will reduce the penalty to 10%.
Understanding Your Benefits: The Personal Impact of SECURE Act 2.0
The SECURE Act 2.0 is greatly expanding the original legislation. Its impact on your retirement plan will be dependent on the type of company and group plan in place.
If you are unsure what changes you will be eligible for, or what changes will be impacting you, check with your human resource department, retirement plan’s financial advisor, and/or the owner, if the company is small enough.
About the Retirement Plan Authors
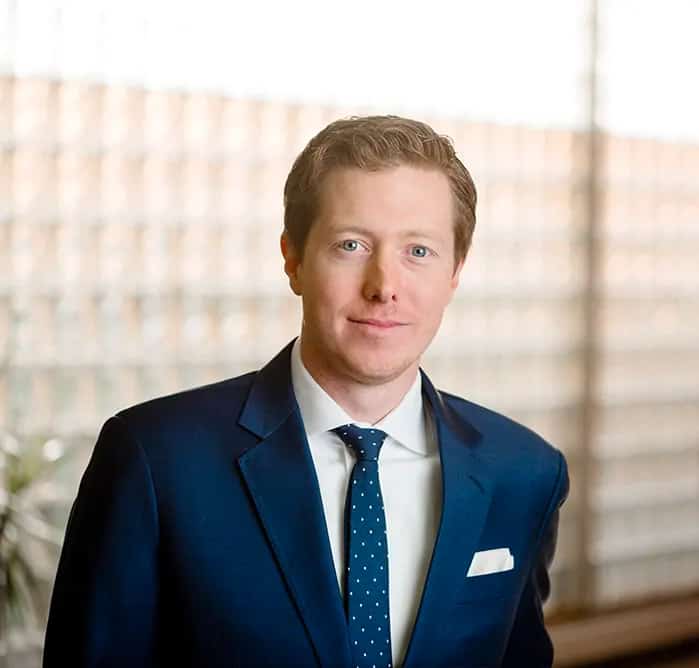
Alexander Langan, J.D., serves as the Chief Investment Officer at Langan Financial Group. In this role, he manages investment portfolios, acts as a fiduciary for group retirement plans, and consults with clients regarding their financial goals, risk tolerance, and asset allocation.
With a focus on ERISA Law, Alex graduated cum laude from Widener Commonwealth Law School. He then clerked for the Supreme Court of Pennsylvania and worked in the Legal Office of the Pennsylvania Office of the Budget, where he assisted in directing and advising policy determinations on state and federal tax, administrative law, and contractual issues.
Alex is also passionate about giving back to the community, and has participated in The Foundation of Enhancing Communities’ Emerging Philanthropist Program, volunteers at his church, and serves as a board member of Samara: The Center of Individual & Family Growth. Outside of work and volunteering, Alex enjoys his time with his wife Sarah, and their three children, Rory, Patrick, and Ava.
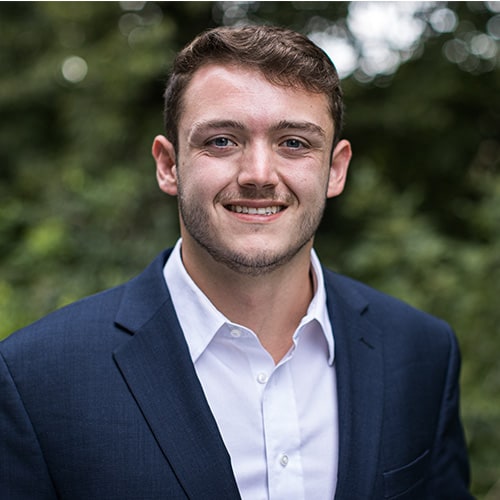
Harry Claypool currently serves as an Associate 401(k) Advisor at Langan Financial Group where he assists Alex in servicing retirement plans, preparing plan reviews, and handling administrative work.
In his free time, Harry enjoys visiting new restaurants, spending time with friends and family, and watching the Eagles.
About Langan Financial Group: 401(K) Financial Advisors
For everything you’ve built.
Your savings. Your business. Your family’s future. Each deserves thoughtful planning that starts with what matters to you.
Langan Financial Group provides financial planning and investment management for individuals, families, and business owners. With offices in Camp Hill and York, Pennsylvania, we serve clients throughout Central Pennsylvania.
We help you work through questions about retirement income, investment decisions, Social Security, and how taxes may affect your financial plan. Our approach starts with understanding your goals, your financial picture, and your comfort with investment risk. From there, we help you evaluate your options and develop a plan that can evolve as your life changes.
We also help businesses and organizations evaluate workplace retirement plans and understand their responsibilities as plan sponsors.
Disclosure
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice.
Please consult legal or tax professionals for specific information regarding your individual situation.
The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security.