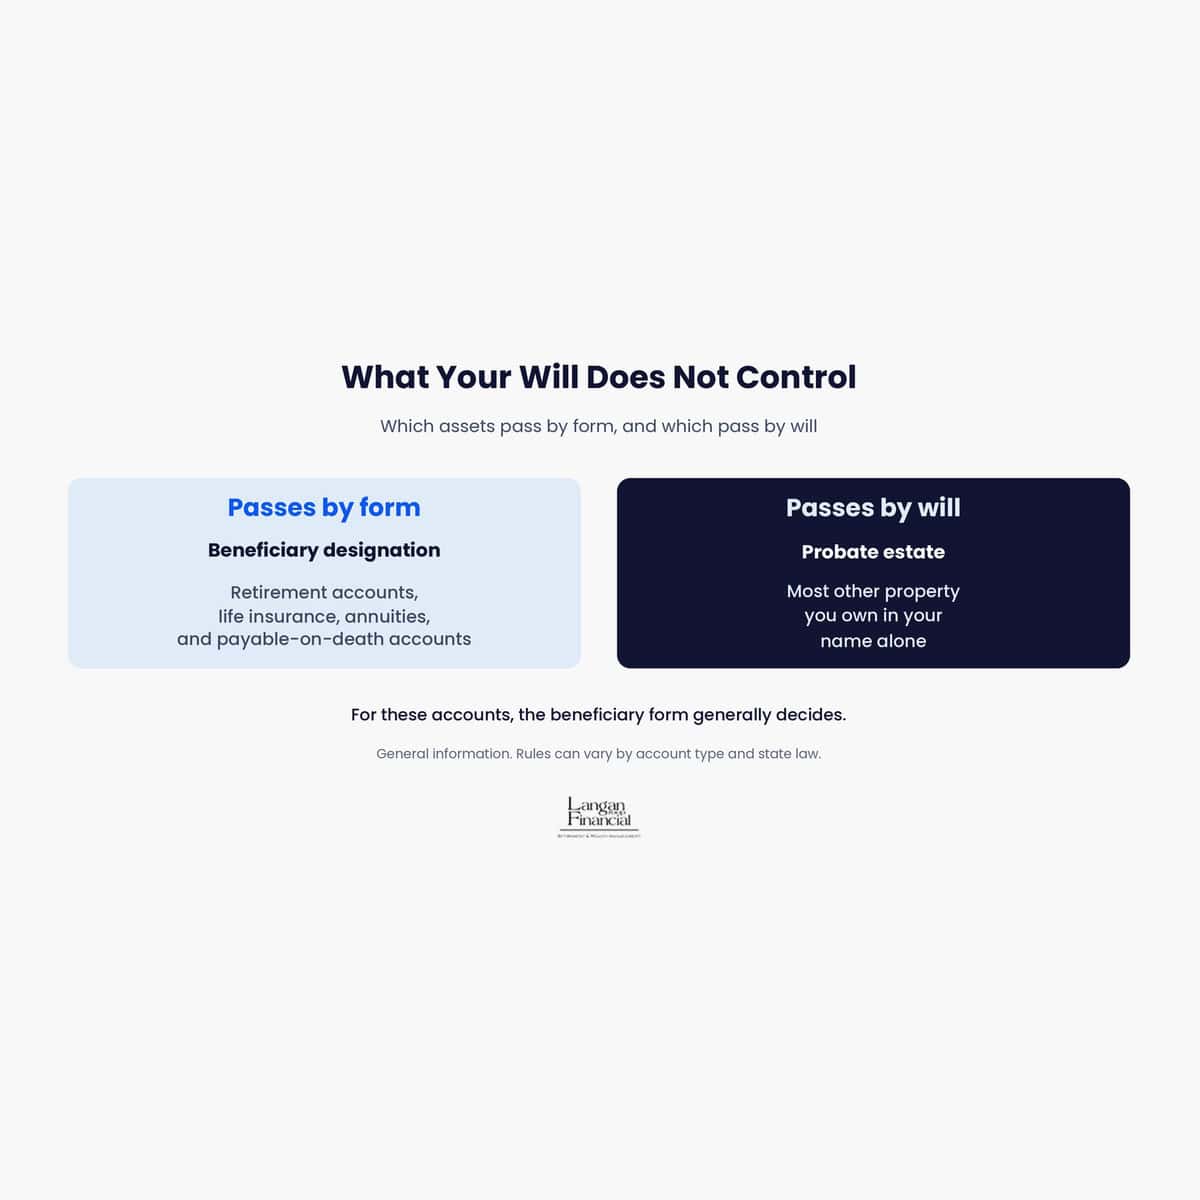
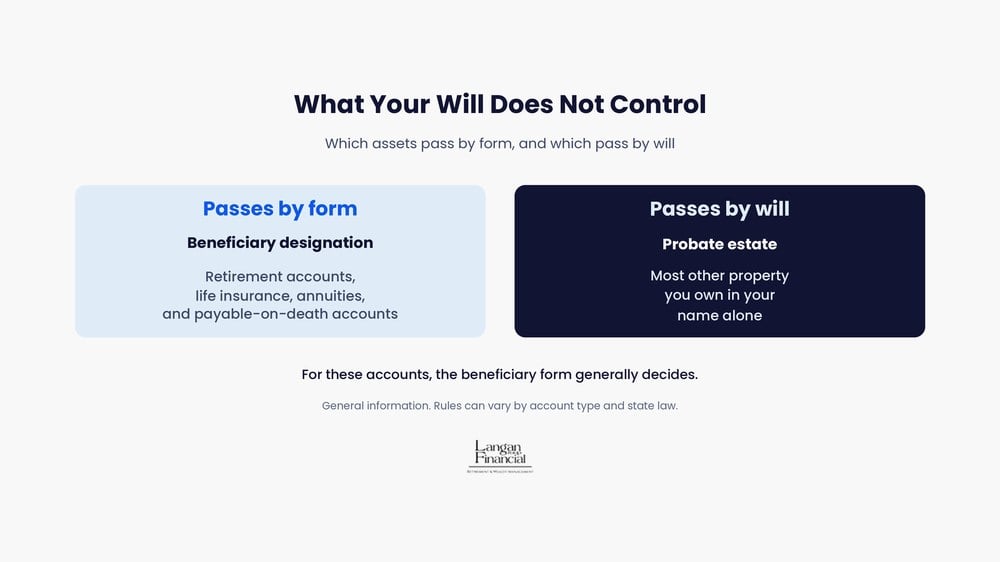
Most people picture a will as the document that settles everything. For a large share of what you own, it does not.
Beneficiary designations are the forms you filled in when you opened a retirement account or bought a life insurance policy. They name who inherits that account, and for those accounts the form generally controls.
Still working: your employer plan is likely the largest single item on that list, and it may hold more than everything your will covers.
Already retired: The same forms are still in force, and the names on them may be older than your current wishes.
Either way, it sits alongside the rest of your estate and legacy plans.
Which Accounts Your Will Does Not Control
The clearest way to think about it is two separate lists.
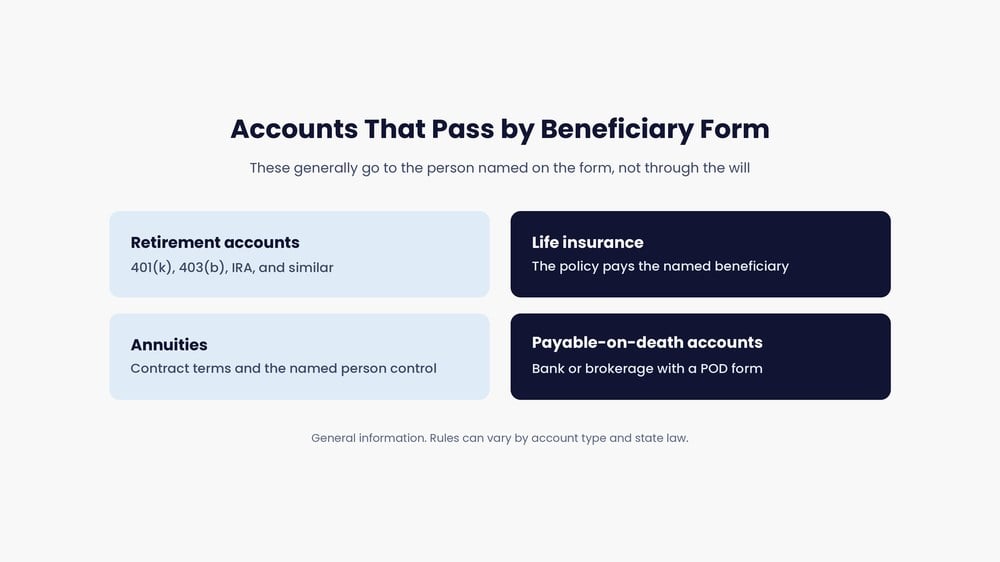
- Passes by the form: retirement accounts such as a 401(k), 403(b), or IRA, life insurance policies, annuities, which are insurance contracts that pay out under their own terms, and bank or brokerage accounts with a payable-on-death form, which names who receives the balance directly.
- Passes by the will: most other property you own in your name alone.
Knowing which of your accounts sits on which list is the starting point for the rest of your weekly planning reading.
The two lists do not talk to each other. As an example, if a will leaves everything equally to three children but the IRA form names only one of them, the IRA generally goes to that one person. The will divides what is left over, not the IRA.
Why this catches people: the will is the document everyone remembers signing. The beneficiary form is the one filled in during onboarding at a job, often years ago, and rarely looked at since.
Where the Money Goes First
Each form has two lines that matter.
The primary beneficiary is paid first. The contingent beneficiary is paid only if no primary is living.
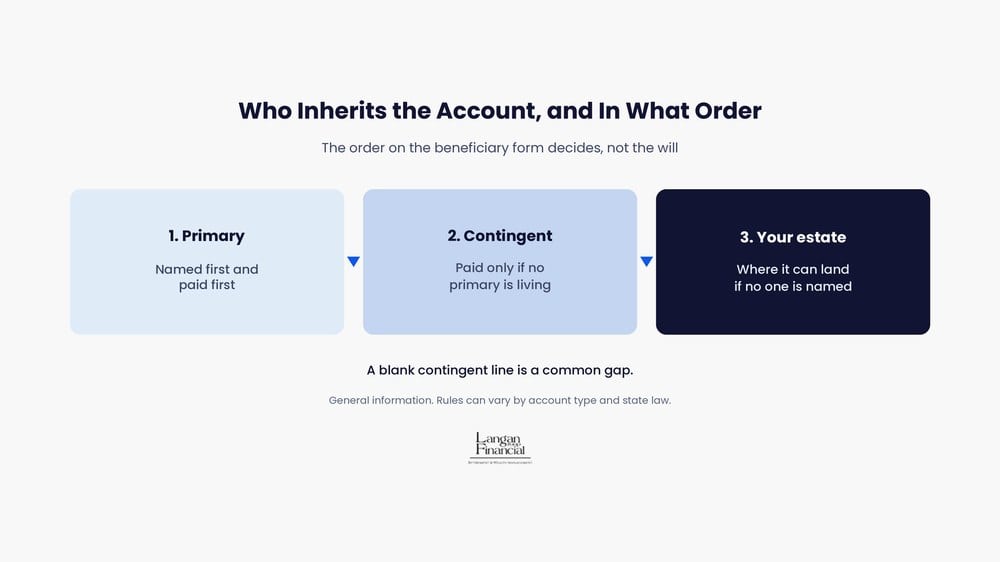
If the primary is not living and no contingent is named, the account may pass to your estate and go through probate, the court process that settles what a will covers. That changes who receives it, and it changes the withdrawal rules that apply to the account.
It also interacts with how the rest of your money is arranged, including how retirement income is taxed for whoever receives it,.
When the Will and the Form Name Different People
This is where beneficiary designations cause the most trouble, and it is rarely because anyone made a mistake.
As an example, a will written five years ago may leave everything equally to three children, while a 401(k) form signed fifteen years ago names one of them, or a former spouse, or no one at all.
The will does not correct the form. The account follows the form, and the will divides what is left.
Worth confirming rather than assuming. Divorce does not automatically remove a former spouse in all situations. Some states revoke by statute, some do not, and certain employer plans are governed by federal law that can preempt state rules. An estate planning attorney can tell you which applies to your accounts. For what to check on each form, see how to review your beneficiary designations.
Who You Name Affects How Fast They Withdraw
This part changed recently enough that many forms were signed before it did.
For accounts inherited after 2019, most non-spouse heirs of a retirement account have ten years to empty it, rather than spreading withdrawals across a lifetime. A surviving spouse generally keeps more options, and a narrow group of other heirs does as well.
Here is why that matters to the person inheriting. A traditional retirement account is taxed as ordinary income when it comes out. Ten years is a shorter window than a lifetime, so the same balance is spread across fewer tax years, and each withdrawal stacks on top of whatever that person already earns.
So the name on the form affects more than who receives the money. It can also shape the tax year of whoever inherits it.
Still working: an adult child inheriting an account may be in their highest-earning years when the ten-year window closes.
Already retired: the same is true, and it is one reason some households look at which account each beneficiary receives rather than splitting everything evenly.
For couples, it is worth asking alongside whether the plan still works for one person.
How to Check Your Own Forms
Beneficiary designations are among the few parts of an estate plan you can check yourself, this week, without an appointment.
Start by listing the accounts that pass by form. Retirement accounts, life insurance, annuities, which are insurance contracts, and any bank or brokerage accounts with a payable-on-death form, which names who receives the balance directly.
Then find out who is named as primary and contingent on each one. Once you have that in front of you, we can look at it with you and see how it fits the rest of your plan.
Still working: include any plan from a former employer. Those are the accounts most likely to carry an old name.
Already retired: include annuities and any payable-on-death bank accounts, which are easy to forget because they rarely generate paperwork.
Many of the accounts that pass by form are the same ones you draw from in retirement.
Our free review guide, Who Inherits Each Account, has a line for each account and a short list of what to look for as you go.
Speak With an Advisor Today
Beneficiary designations sit alongside the rest of your retirement picture. We can talk through how yours fit with your income plan, your tax situation, and what you want to leave behind.
Or call 717-288-1880
Common Questions About Beneficiary Designations
Do beneficiary designations override a will?
For the accounts they cover, generally yes. A beneficiary designation is the form naming who receives a retirement account, life insurance policy, annuity, or payable-on-death account. Those assets pass by the form rather than through the will. Rules can vary by account type and state law.
Which accounts pass by beneficiary designation?
Commonly retirement accounts such as a 401(k), 403(b), or IRA, life insurance policies, annuities, and bank or brokerage accounts with a payable-on-death or transfer-on-death form. Most other property you own in your name alone passes through your will.
What happens if no beneficiary is named?
It depends on the account and the provider. The account may pass to a default named in the plan document, or to your estate and through probate. Passing to the estate can change both who receives the money and the schedule on which it has to be withdrawn.
Does a divorce remove a former spouse from a beneficiary designation?
Not automatically in all situations. Some states revoke a former spouse by statute, some do not, and certain employer plans are governed by federal law that can preempt state rules. This is worth confirming with an estate planning attorney rather than assuming.
What is the difference between a primary and a contingent beneficiary?
The primary beneficiary is paid first. The contingent beneficiary is paid only if no primary beneficiary is living. A blank contingent line is a common gap, because it leaves no instruction if the primary beneficiary is no longer living.
Sources
Internal Revenue Service, Retirement Topics: Beneficiary
Internal Revenue Service, Publication 590-B, Distributions from Individual Retirement Arrangements
SECURE Act of 2019, and IRS final regulations on required minimum distributions, July 2024
Employee Retirement Income Security Act of 1974, spousal consent provisions
This article is provided for informational and educational purposes only and does not constitute investment advice, financial planning advice, tax advice, or legal advice. All investing involves risk, including potential loss of principal. Past performance is not a guarantee of future results. Individual results will vary based on specific financial circumstances. Beneficiary designation rules can vary by account type and state law. Estate planning decisions should be made in consultation with a qualified estate planning attorney. Please consult a qualified financial, tax, or legal professional before making any financial decisions. Securities offered through PKS Securities, Inc., a Broker-Dealer, Member FINRA/SIPC. Advisory services offered through Langan Financial Group, LLC, a Registered Investment Adviser. Registration does not imply a certain level of skill or training.